Bitcoin Allocation: Risk, Volatility, and Diversification in a Portfolio
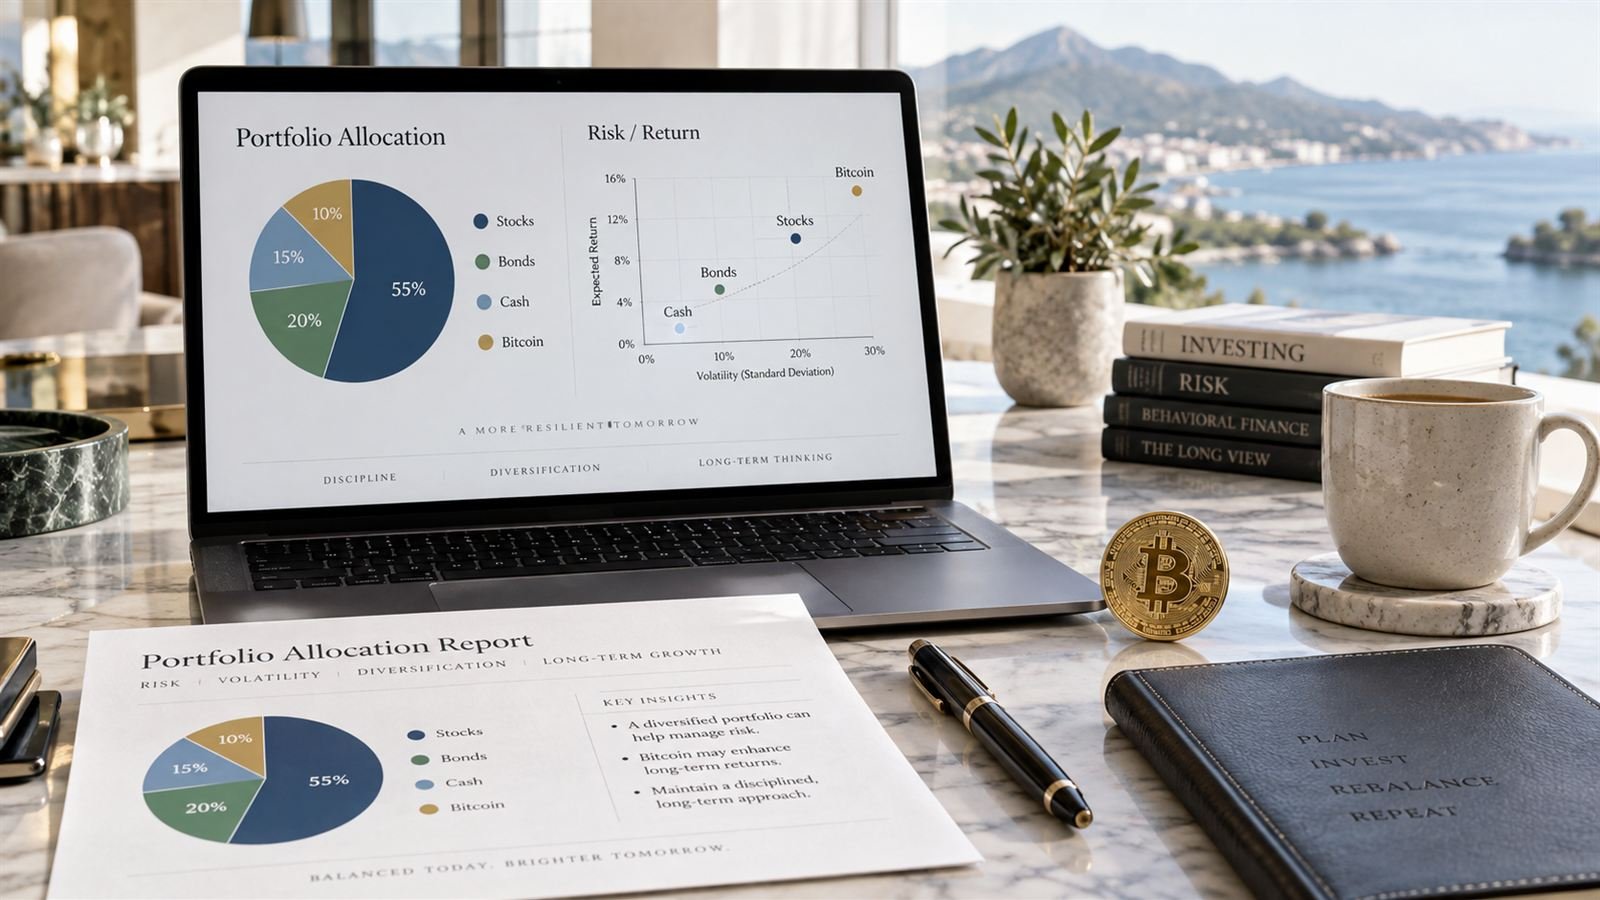
The hardest question about Bitcoin in a portfolio is not whether its historical return has been high. It is how much risk an investor is accepting to gain exposure to a volatile asset whose correlations, market structure, regulation, and adoption are still evolving.
That distinction matters because a small capital allocation can create a much larger share of portfolio risk.
BlackRock has illustrated this with a risk-budgeting framework. In its portfolio work, the firm estimated that a 1% Bitcoin position in a traditional 60/40 stock-bond portfolio could contribute roughly 2% of total portfolio risk, while a 2% position could contribute about 5%. At a 4% allocation, its estimate rose to roughly 14% of portfolio risk. BlackRock therefore described roughly 1% to 2% as a reasonable range for investors who believe in broader adoption and can tolerate sharp drawdowns.
That is one framework, not a universal allocation rule.
Fidelity Digital Assets argued in its 2026 research that institutional investors and money managers should have a well-informed rationale for maintaining a zero-weight position. CoinShares’ May 2026 fund-manager survey found a 1% median digital-asset allocation among respondents, although the weighted average was only 0.1% because the sample included a larger share of institutions with very low exposure.
Taken together, the useful question is not “What percentage should everyone own?” It is “What does a given Bitcoin allocation do to this portfolio’s risk, liquidity, drawdown, and investment thesis?”
Key Takeaways
The points below summarize how a bitcoin allocation changes the risk of a portfolio.
- Capital Weight Is Not Risk Weight: Bitcoin’s volatility means a small position can contribute disproportionately to total portfolio risk.
- There Is No Universal Percentage: A reasonable allocation depends on risk tolerance, liabilities, time horizon, liquidity needs, and investment beliefs.
- Diversification Is Conditional: Bitcoin has shown periods of low correlation with traditional assets, but correlations can rise during market stress.
- Rebalancing Matters: A volatile asset can quickly become a much larger or smaller part of the portfolio than originally intended.
- Use Scenario Analysis: Investors should test severe drawdowns, not just expected returns.
- Separate Strategic from Tactical Exposure: A long-term diversifier thesis is different from a short-term macro or momentum trade.
- A Zero Allocation Is Also a Decision: It can be appropriate, but it should still be based on explicit assumptions.
Start With the Portfolio, Not Bitcoin
Asset-allocation discussions often begin with the asset: Bitcoin has a fixed supply, Bitcoin has had strong historical returns, Bitcoin is volatile, Bitcoin trades globally.
Portfolio construction works in the opposite direction.
Start with the investor’s objective, required return, tolerance for loss, time horizon, cash needs, existing equity and bond exposure, concentration, tax constraints, and governance rules.
Only then ask whether Bitcoin improves the portfolio under those constraints.
This prevents an asset narrative from becoming an allocation decision by default.
Capital Allocation and Risk Contribution Are Different
Suppose a portfolio has $100,000 and adds $2,000 of Bitcoin. The capital weight is 2%.
That does not mean Bitcoin contributes 2% of the risk.
Risk contribution depends on Bitcoin volatility, volatility of the other assets, correlation with those assets, and portfolio weights.
An asset with much higher volatility can drive a larger share of changes in portfolio value than its capital weight suggests.
BlackRock’s published risk-budget example illustrates this point:
| Bitcoin Weight | Estimated Share of Portfolio Risk in BlackRock Example |
|---|---|
| 1% | about 2% |
| 2% | about 5% |
| 4% | about 14% |
The figures come from a specific methodology and a traditional 60/40 reference portfolio. They should not be copied into every investor’s plan. Their value is conceptual: risk can accelerate faster than capital weight.
BlackRock’s published 60/40 portfolio example estimated that 1%, 2%, and 4% Bitcoin weights could contribute about 2%, 5%, and 14% of portfolio risk, respectively. The estimates are methodology-specific and are not allocation recommendations.
Why Small Allocations Get So Much Attention
Bitcoin’s return distribution has historically been unusual.
It has delivered large upside periods alongside repeated deep drawdowns. That combination means a small allocation can materially influence long-term results in either direction.
BlackRock’s August 2026 research said its updated 10-year historical analysis found that a 1% to 2% allocation would have improved risk-adjusted returns in a traditional 60/40 portfolio over the period studied. Past performance does not establish that the result will repeat.
The lesson is not “1% to 2% always works.” The lesson is that a small allocation can be economically meaningful when the asset has high volatility and asymmetric historical returns.
Diversification Depends on Correlation, and Correlation Moves
Bitcoin is sometimes presented as either completely uncorrelated with traditional assets or simply another risk asset.
Neither description is stable enough to serve as a permanent rule.
BlackRock’s 2026 work describes Bitcoin as having a “dual personality”: it can trade alongside risk assets during deleveraging episodes and behave differently during some geopolitical or monetary shocks.
That means correlation should be treated as a changing input.
For portfolio diversification analysis, the useful question is not whether Bitcoin has one fixed correlation number. It is how its relationship with equities, bonds, gold, and cash behaves across different regimes.
An investor should therefore examine long-term average correlation, rolling correlation, stress-period correlation, downside correlation, and correlation during liquidity events.
Diversification is most valuable when assets behave differently when the portfolio needs it most.
A Low Correlation Asset Can Still Create Large Drawdowns
Low correlation does not mean low risk.
An asset can move independently of stocks and bonds while still falling 50% or more.
That distinction is critical.
Consider a simplified example. A portfolio has 59% equities, 39% bonds, and 2% Bitcoin.
If Bitcoin falls 50% while the other assets are unchanged, the direct portfolio impact is roughly 1 percentage point before rebalancing or interaction effects.
If Bitcoin later grows enough to become 8% of the portfolio and then falls 50%, the direct impact is roughly 4 percentage points.
The asset’s changing weight matters.
Rebalancing Is Part of the Allocation Decision
A Bitcoin target without a rebalancing rule is incomplete.
Because the asset can move rapidly, a 1% target can become 2%, 3%, or more after a strong run. It can also shrink below the target after a decline.
Common approaches include calendar rebalancing, threshold rebalancing, contribution-based rebalancing, and discretionary rebalancing.
Calendar Rebalancing
The portfolio returns to target weights on a schedule, such as quarterly or annually.
The advantage is simplicity. The disadvantage is that a fast-moving asset can drift far from target between dates.
Threshold Rebalancing
The position is adjusted when it moves outside a predefined band.
A 2% target might trigger review if it falls below 1% or rises above 3%, for example. Those numbers are illustrative, not recommendations.
Contribution-Based Rebalancing
New contributions are directed toward underweight assets instead of selling the overweight asset.
This can reduce transactions, although it may be too slow after a very large price move.
Whatever method is used, the rule should exist before volatility tests discipline.
Scenario Analysis Is More Useful Than a Single Return Forecast
Bitcoin forecasts can vary dramatically because assumptions about adoption, regulation, market share, monetary demand, and macro conditions vary dramatically.
Portfolio analysis should therefore use scenarios.
A simple framework can test:
| Scenario | Bitcoin Return | Purpose |
|---|---|---|
| Severe downside | -70% | Test loss tolerance |
| Major downside | -50% | Test drawdown impact |
| Moderate decline | -20% | Test routine volatility |
| Flat | 0% | Test opportunity cost |
| Strong gain | +50% | Test weight drift |
| Very strong gain | +100% | Test concentration after appreciation |
If Bitcoin is 1% of a portfolio and falls 70%, the direct capital effect is about -0.7 percentage points if other assets are unchanged.
At a 5% weight, the same Bitcoin decline implies about -3.5 percentage points.
That difference is why allocation sizing matters more than excitement about the asset.
Liquidity Risk Is Not Only About Whether Bitcoin Trades 24/7
Bitcoin is one of the most liquid crypto assets, with deep global markets and regulated investment vehicles in several jurisdictions.
Portfolio liquidity still involves more than trading availability.
An investor using an ETF faces market-hour, spread, tax, and brokerage considerations. A self-custody holder faces transfer, exchange, custody, and operational considerations. A fund may face mandate, custodian, compliance, and redemption constraints.
Institutional investors also need to consider whether their governance and operational infrastructure can support the exposure.
CoinShares’ May 2026 survey found that institutional constraints and regulation remained important barriers to larger digital-asset allocations. That suggests the investment thesis can be stronger than the organization’s ability to implement it.
The Vehicle Changes the Risk
“Bitcoin allocation” can refer to several forms of exposure.
| Exposure Method | Key Risks |
|---|---|
| Direct self-custody | Key loss, operational error, wallet security |
| Custodial exchange | Counterparty and platform risk |
| Spot exchange-traded product | Fund structure, fees, tracking, market hours |
| Futures | Basis, roll, leverage, margin |
| Bitcoin-linked equity | Company-specific operating and financing risk |
Two investors can both report a 2% Bitcoin allocation and hold materially different risks depending on the vehicle.
Do not compare allocations without comparing implementation.
A Strategic Allocation Needs an Investment Thesis
A strategic holding should answer why Bitcoin belongs in the portfolio.
Possible theses include scarcity and adoption, monetary alternative, diversification, asymmetric return potential, hedge against specific monetary or geopolitical risks, or exposure to a growing digital-asset ecosystem.
Those theses are not equivalent.
If the reason is diversification, monitor correlation and risk contribution.
If the reason is monetary hedge, examine behavior during the specific risks being hedged.
If the reason is adoption, track adoption evidence.
A thesis becomes useful when it can be monitored and falsified.
Tactical Exposure Is a Different Decision
A tactical Bitcoin position may be based on liquidity conditions, momentum, ETF flows, macro catalysts, regulatory events, or valuation models.
That is not the same as holding Bitcoin indefinitely as a strategic diversifier.
The distinction affects: time horizon, sizing, rebalancing, exit rules, and evaluation.
A strategic allocation can survive short-term volatility if the thesis remains intact. A tactical position may be closed when the catalyst changes.
What Institutional Surveys Can and Cannot Tell You
CoinShares’ May 2026 fund-manager survey provides an informative snapshot.
The survey drew 26 responses from investors covering roughly $1.3 trillion in assets under management. CoinShares reported a weighted average digital-asset allocation of 0.1% and a median allocation of 1%.
The difference between mean and median matters.
The weighted average was influenced by large institutions with small allocations. The median describes the middle response, not the asset-weighted market.
The survey also found that diversification and client demand together accounted for 63% of respondents’ rationale for adding digital assets, while speculation had declined as a stated motivation.
Useful conclusion: some professional investors are increasingly framing digital assets through portfolio construction rather than only speculation.
Not justified: “Institutions allocate 1% to Bitcoin.” The survey measured digital-asset allocations among a specific sample, not a universal Bitcoin policy.
What a 1%, 2%, and 5% Allocation Means in a Simple Crash
A simple loss table helps make allocation concrete.
Assume Bitcoin falls 60% and every other portfolio asset is unchanged.
| Bitcoin Weight Before Decline | Direct Portfolio Effect |
|---|---|
| 1% | -0.6 percentage points |
| 2% | -1.2 percentage points |
| 5% | -3.0 percentage points |
| 10% | -6.0 percentage points |
Real portfolios do not behave this cleanly because other assets move too and correlations can change.
The table is still useful because it connects a percentage allocation with a plausible loss.
An investor who cannot tolerate the portfolio effect of a severe Bitcoin drawdown has learned something more actionable than a price target could provide.
Allocation Size Should Reflect the Investor’s Loss Budget
A useful way to work backward from risk is to start with the maximum portfolio loss an investor is willing to attribute to Bitcoin in a severe drawdown.
Suppose the planning scenario is a 70% Bitcoin decline. If an investor is willing to accept at most a 1% direct hit to total portfolio value from that scenario, the rough capital weight implied by simple arithmetic is about 1.43%:
Maximum Bitcoin Weight = Maximum Acceptable Portfolio Loss / Assumed Bitcoin Drawdown
1% / 70% = 1.43%
This is not a complete portfolio optimization model. It ignores correlations, changes in the other assets, taxes, rebalancing, and nonlinear effects. It is useful because it starts with a loss budget rather than a return target.
The same exercise can be repeated for different assumptions:
| Maximum Direct Portfolio Loss | Assumed Bitcoin Drawdown | Illustrative Maximum Weight |
|---|---|---|
| 0.5% | 70% | 0.71% |
| 1.0% | 70% | 1.43% |
| 2.0% | 70% | 2.86% |
| 3.0% | 70% | 4.29% |
An investor can then compare those simple capital-loss limits with a risk-budget model that also accounts for volatility and correlation. If both methods indicate that the desired allocation is too large for the investor’s tolerance, that is more informative than searching for a more optimistic Bitcoin forecast.
Concentration Can Emerge After Success
One of the less obvious allocation risks is success.
If Bitcoin rises far faster than the rest of the portfolio, it can become a concentration even if the initial allocation was small.
For example, imagine: $98,000 in traditional assets and $2,000 in Bitcoin.
If the traditional assets remain unchanged and Bitcoin quadruples, Bitcoin becomes $8,000 in a $106,000 portfolio, or about 7.5%.
The investor no longer has a 2% Bitcoin portfolio. The asset has become large enough to influence the overall risk budget much more strongly.
This is why rebalancing rules belong in the original allocation decision.
Questions to Answer Before Setting a Bitcoin Allocation
Before choosing any percentage, write down the answers to these questions:
- What is the reason for owning Bitcoin?
- What evidence would weaken that thesis?
- What maximum portfolio loss from Bitcoin is tolerable?
- What vehicle will be used?
- Who controls custody?
- What is the rebalancing policy?
- What is the tax treatment in the investor’s jurisdiction?
- What happens if Bitcoin becomes 2x or 4x the target weight?
- What happens if Bitcoin falls 70%?
- Is the position strategic or tactical?
If these questions cannot be answered, the allocation is not fully designed.
Frequently Asked Questions
These questions cover the points readers most often need to verify before acting on the information above.
What Is a Reasonable Bitcoin Allocation?
There is no universal percentage. Some institutional research has discussed 1% to 2% ranges for certain diversified portfolios, but the appropriate size depends on the investor’s risk tolerance, objectives, and implementation.
Why Can a 2% Bitcoin Position Matter So Much?
Bitcoin has historically been much more volatile than stocks and bonds. A small capital weight can therefore contribute a larger share of total portfolio risk.
Does Bitcoin Diversify a Stock Portfolio?
It can, depending on the period and market regime. Correlation is not constant, and Bitcoin can become more correlated with risk assets during stress.
Should Bitcoin Be Rebalanced?
A rebalancing policy can keep the position closer to its intended risk budget. Without one, large price moves can turn a small allocation into a much larger concentration.
Is Buying a Bitcoin ETF the Same as Holding Bitcoin?
No. The economic exposure may be similar, but custody, trading hours, fees, operational risk, and ownership structure differ.
Is Zero Bitcoin Allocation Wrong?
No. A zero allocation may fit an investor’s objectives or constraints. The useful standard is to make the decision explicitly rather than by default.
Resources
The following sources provide the primary or specialist evidence used to verify the claims and frameworks above.