
ACH vs Wire Transfer: Speed, Cost, Limits, and Best Uses
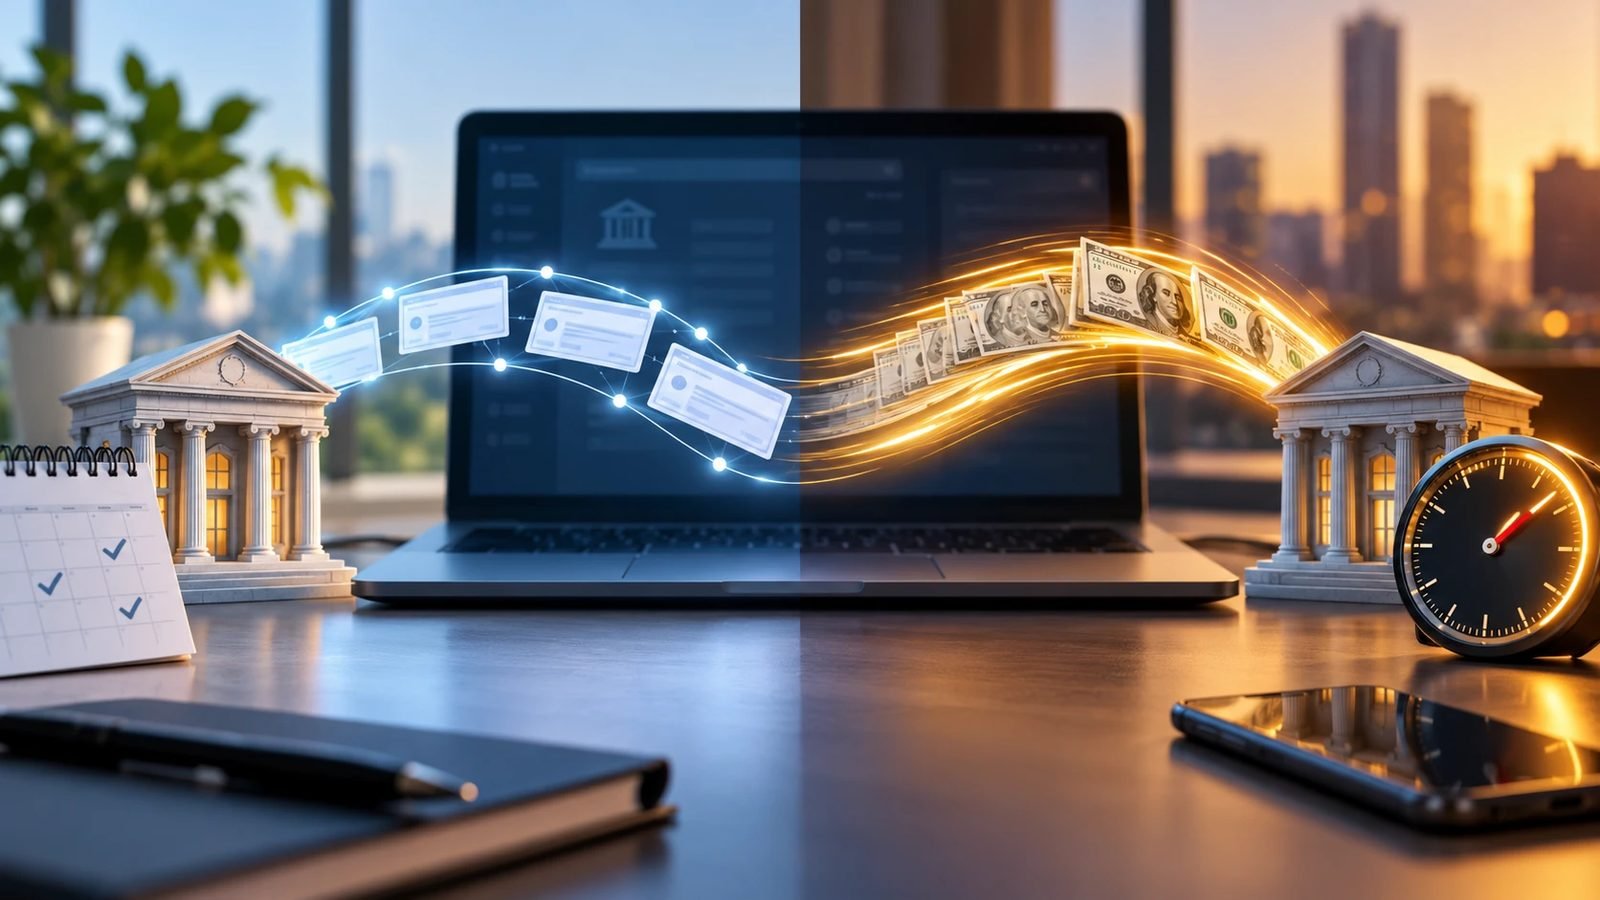
The ACH vs wire transfer choice comes down to how a payment settles. ACH payments move through the Automated Clearing House Network, mostly in batches, and are built for payroll, bills, and routine account transfers. Wire transfers move through systems such as the Federal Reserve's Fedwire Funds Service, where each payment settles on its own, in real time, with finality.
For most routine payments, ACH is the lower-cost option. For urgent or large payments that must settle with certainty, a wire is often the tool banks and businesses reach for. Fees, timing, and limits still vary by bank, so the details below explain how each system works and where each one fits.
Key Takeaways
- ACH payments are electronic credits and debits processed mostly in batches under Nacha rules.
- The two U.S. ACH Operators are the Federal Reserve and The Clearing House.
- Fedwire settles each payment individually in real time, and a processed payment is final and irrevocable.
- Nacha estimates about 80% of ACH payments settle in one banking day or less.
- In Q3 2026 the ACH Network carried 9.3 billion payments worth $25.6 trillion.
- In September 2026 Fedwire handled 19.8 million transfers worth about $105.15 trillion, an average of $5.31 million each.
- Banks often charge for wires, while ACH transfers are often free or low-cost for consumers.
- ACH has defined return and error rules, while a completed wire is hard to recover.
- The right rail depends on amount, urgency, destination, cost, and fraud risk.
ACH vs Wire Transfer at a Glance
The table compares the two systems on the points that most often decide which one a person or business uses. Fees and timing vary by bank and transfer type, so treat it as a summary of how the systems are built rather than a price list.
| Feature | ACH Transfer | Wire Transfer |
|---|---|---|
| Network | ACH Network | Fedwire or another wire system |
| Processing | Mostly batch processing | Individual, real-time settlement |
| Typical speed | Same day to two banking days | Often the same business day for domestic wires |
| Cost to consumer | Often free or low-cost | Often carries a bank fee |
| Common uses | Payroll, bills, recurring and routine transfers | Urgent, high-value, time-sensitive payments |
| Reversals | Defined ACH return rules | Final once processed |
| Domestic reach | All U.S. bank and credit union accounts | Institutions that take part in wire networks directly or indirectly |
| Fraud concern | Consumer EFT protections can apply | Finality makes recipient checks critical |
The biggest structural difference sits in the second row. ACH groups many payments and settles them together, while a wire settles one payment at a time. Most of the other ACH vs wire transfer differences in speed, cost, and reversibility follow from that design choice.
How ACH Transfers Work
The ACH Network connects U.S. banks and credit unions so they can send electronic credits and debits to each other. A paycheck deposited by an employer is an ACH credit. A utility company pulling a monthly bill from a checking account is an ACH debit.
The Path of an ACH Payment
For an ACH credit, the payer tells its bank to send money. That bank is the Originating Depository Financial Institution, or ODFI. It passes the payment to an ACH Operator, which delivers it to the recipient's bank, the Receiving Depository Financial Institution, or RDFI. The RDFI then posts the money to the recipient's account under Nacha's settlement rules.
Two Operators, One Network
Nacha, which governs the ACH Network, states that there are two ACH Operators: the Federal Reserve and The Clearing House. The two operators exchange payments with each other, so a bank connected to either one can reach every other bank. To the payer and the recipient, the network works as one system.
ACH Is Much Larger Than Many Consumers Realize
The ACH Network is one of the largest payment systems in the United States by number of payments. According to Nacha's third-quarter 2026 network figures, the network carried 9.3 billion payments worth $25.6 trillion in Q3 2026. Those totals were 5.9% and 10.2% higher than in the same quarter of 2025.
Same Day ACH Is Growing Fastest
Same Day ACH accounted for 470.4 million of those Q3 2026 payments, up 36.7% from a year earlier, with a value of $1.3 trillion. Nacha reported that year-to-date 2026 Same Day ACH volume reached 1.3 billion payments worth more than $3.6 trillion. Faster settlement is clearly drawing more payments onto the network.
Paychecks and Benefits Run on ACH
Nacha's fact sheet says some 93% of American workers receive their pay through the ACH Network, and 99% of Social Security payments use it. It also says the network reaches all U.S. bank and credit union accounts. Those figures explain why ACH carries far more than small transfers between friends or family members.
How Wire Transfers Work
A wire transfer sends a payment instruction between financial institutions through a wire system. For U.S. dollar payments, the main system is the Fedwire Funds Service, which the Federal Reserve Banks run. A customer asks their bank to send a wire, and the bank submits the payment on the customer's behalf.
Real-Time Gross Settlement
The Federal Reserve describes Fedwire as a real-time gross settlement system that lets participants make funds transfers that are immediate, final, and irrevocable once processed. "Gross" means each payment settles on its own rather than being netted against others in a batch. "Real time" means that settlement happens as soon as the payment is processed.
What Finality Means for the Sender
When a Fedwire payment is processed, the sending bank's Federal Reserve account is debited and the receiving bank's account is credited. At that point the payment cannot be unwound at the system level. That certainty is why wires are common for large transactions, and it is also why sending a wire to the wrong person is so costly.
Fedwire Handles Fewer Payments but Far More Value Per Transfer
Fedwire processes far fewer payments than ACH, but each one is typically much larger. Federal Reserve Financial Services data show that in September 2026 Fedwire handled 19,786,425 transfers worth about $105.15 trillion. The average transfer was about $5.31 million, and average daily value was about $5.01 trillion.
Comparing the Two Systems
For comparison, the whole ACH Network moved $25.6 trillion across the full third quarter of 2026. Fedwire moved roughly four times that value in a single month, with a small fraction of the payment count. The gap reflects the systems' jobs: ACH handles very large volumes of routine payments, while Fedwire carries large, time-critical transfers.
What the Averages Hide
The $5.31 million average is pulled up by large interbank and institutional payments. Consumer wires for a home closing or a family transfer are typically far smaller. The average shows what the system is built for, not what a typical household sends, so it should not be read as a typical customer wire.
Which Is Faster: ACH or Wire?
A domestic wire can often arrive the same business day when the sender's bank receives the request before its cutoff time. Fedwire itself processes accepted payments in real time during its operating hours. Delays usually come from bank cutoffs, fraud checks, missing details, or weekends and holidays rather than from Fedwire. The detailed timing rules are covered in how long a wire transfer takes, including cutoff times and international delays.
ACH Settlement Windows
ACH timing has more variety. Nacha estimates that 80% of ACH payments, credits and debits combined, settle in one banking day or less across regular and Same Day ACH. Nacha says ACH credits can settle the same day, the next banking day, or in two banking days, while ACH debits settle the same day or the next banking day.
Same Day ACH Has Narrowed the Gap
Same Day ACH lets eligible payments settle during the same banking day. Its 36.7% growth in Q3 2026 shows how much of the network now moves quickly. Because of that, the ACH vs wire transfer speed gap is now less about slow versus fast and more about certainty, finality, and the type of payment.
A September 2026 Rule Improved ACH Funds Availability
Nacha changed its funds-availability rule for non-Same Day ACH credits on September 18, 2026. Receiving banks must now make those funds available no later than 9:00 a.m. in the receiving bank's local time on the settlement date.
What Changed
The new rule removed an older condition tied to when the receiving bank got the ACH file, which had been set at 5:00 p.m. local time. Without that condition, the 9:00 a.m. deadline applies regardless of when the file arrived the day before. Nacha said the change will speed up access to funds for some next-day ACH credits.
What It Means for Recipients
For someone waiting on a next-day ACH deposit, the change can mean money is usable earlier on the settlement date. It does not turn regular ACH into Same Day ACH, and it does not change how long a payment takes to settle. It changes when the receiving bank must release funds.
Which Costs More?
For bank customers, ACH transfers are often free or low-cost. Many consumer checking accounts include ACH transfers at no direct charge, and payroll and bill payments rarely cost the payer anything per item. Wires, by contrast, commonly carry a fee each time they are sent or received.
Typical Wire Charges
Wire pricing is set by each bank, and the fees a sender may see fall into a few groups:
- Outgoing Domestic Wire: A fee charged by the sending bank for each domestic wire.
- Incoming Wire: A fee some banks charge to receive a wire.
- International Wire: A higher fee for sending money abroad.
- Intermediary Bank: A charge deducted by a bank in the middle of an international transfer.
- Currency Conversion: A cost built into the exchange rate on foreign-currency wires.
Fee schedules differ widely, so the sender's own bank is the only reliable source for the exact price of a given wire.
Network Costs Are Not Consumer Prices
Bank fees should not be confused with what the networks charge banks. The Federal Reserve's 2026 FedACH schedule lists a forward or return item fee of $0.0035, with lower rates at higher volume tiers. A bank pays those tiny network fees but sets its own customer prices, which cover far more than the network charge alone.
Are Wire Transfers Safer?
In the ACH vs wire transfer safety debate, whether a wire is "safer" depends on which risk is being measured. A wire is very safe in one sense and risky in another, and the two ideas are often confused.
Settlement Risk
Fedwire offers strong settlement finality. Once a payment is processed, it is final and irrevocable at the payment-system level, so the recipient's bank does not have to worry that the money will be pulled back. That certainty is valuable for property closings, large business payments, and other deals where both sides need to know the money has moved.
Fraud Risk
The same finality works against the sender when money goes to the wrong account or to a scammer. A bank may send a return request, but recovery is not guaranteed after a wire completes. That is why recipient details should be confirmed through a trusted phone number or known contact before an important wire is sent.
ACH Has Different Error and Return Mechanisms
ACH payments follow Nacha rules, and consumer accounts also fall under the Electronic Fund Transfer Act and Regulation E. Those rules give consumers specific rights when an electronic transfer is unauthorized or wrong, along with steps banks must follow to investigate errors.
Unauthorized Transfers Under Regulation E
The CFPB's electronic fund transfer guidance answers yes to whether a transfer started by a fraudster with stolen account credentials counts as an unauthorized electronic fund transfer under Regulation E. A consumer's liability then depends on the facts and on how quickly the bank is notified.
Protections Are Not a Safety Net for Everything
These protections help, but they do not cover every situation. Some cases, such as a consumer who knowingly sends money to a scammer, can fall outside the unauthorized transfer rules. Suspicious payment requests still deserve a pause and an independent check before any money moves, whichever rail is used.
Can an ACH Transfer Be Reversed?
ACH has return processes for specific situations, and the reason for the return decides which rules apply. Common return situations include these:
- Unauthorized Debits: A debit the account holder did not approve.
- Incorrect Account Information: A payment sent to an account number that does not match.
- Insufficient Funds: A debit the account cannot cover.
- Closed Accounts: A payment sent to an account that no longer exists.
- Duplicate or Erroneous Entries: A payment sent twice or in the wrong amount.
That does not mean any ACH payment can be cancelled after it settles. Return rights depend on the entry type, the reason, the timing, the account type, and the rules that apply to that payment.
Can a Wire Transfer Be Cancelled?
A domestic bank wire is much harder to reverse once it has been processed. Fedwire settlement is final and irrevocable at the system level. A sending bank can send a return request, but the receiving side is not required to return a valid payment just because the sender changed their mind.
International Remittances Are Different
Some international transfers sent by consumers count as remittance transfers under federal rules. For a covered remittance, the sender generally has 30 minutes after paying to cancel, as long as the recipient has not already picked up the money or had it deposited. The provider must disclose these rights when the transfer is made.
Before the Wire Is Released
A wire that the bank has not yet released into the payment system may still be stoppable. Speed counts here. A sender who spots a mistake should contact the bank at once and ask whether the payment has been sent, rather than waiting for a pending status to change.
When ACH Usually Makes More Sense
ACH tends to fit payments where low cost and routine handling count for more than instant finality. Typical examples include these:
- Payroll: Direct deposit of wages and salaries.
- Recurring Bills: Utilities, insurance premiums, and loan payments.
- Account-to-Account Transfers: Moving money between a person's own accounts at different banks.
- Vendor Payments: Routine business payments to suppliers.
- Government Payments: Tax refunds and federal benefits.
For many of these, Same Day ACH now offers speed close to a wire at a lower cost, though the exact price and timing depend on the bank.
When a Wire Usually Makes More Sense
A wire tends to fit payments where speed, size, and certainty outweigh the fee. Common examples include these:
- Real Estate Closings: Down payments and closing funds that must arrive on a set day.
- Large Business Payments: Time-sensitive transfers between companies.
- Urgent Account Funding: Money that must be available the same business day.
- International Transfers: Payments that need bank-to-bank wire connections abroad.
For large transfers, wire instructions should be confirmed through a known phone number or contact. Wire fraud often relies on altered payment instructions in an email rather than on any weakness in the settlement system. The full mechanics of a wire, including the details a bank needs, are covered in what a wire transfer is.
ACH vs Wire Transfer Is Not the Only Choice
U.S. payment options now go beyond ACH and wires. Instant payment systems such as FedNow and RTP, card networks, and fintech apps all move money between accounts. Nacha itself describes ACH, instant payments, cards, and wires as complementary options rather than rivals.
How Digital Payments Fit In
Many consumer apps sit on top of these rails. A peer-to-peer app or digital wallet may fund a payment by card or by ACH behind the scenes. The growth of digital wallets is tracked in PayPal statistics, which shows how much payment volume now runs through platforms rather than direct bank transfers.
Matching the Rail to the Payment
The ACH vs wire transfer decision is therefore one part of a wider question: which rail best fits a payment's amount, urgency, cost, and risk. A monthly bill, a home closing, and a split dinner bill each point to a different answer, and the same person may use all of them in one week.
Frequently Asked Questions
Is ACH Faster Than a Wire Transfer?
Usually not for urgent domestic payments. Fedwire settles accepted payments in real time, while ACH payments typically settle the same day or within one to two banking days.
Is ACH Cheaper Than a Wire?
For consumers, ACH is usually cheaper and often free. Banks commonly charge for domestic and international wires, although exact fees vary from one bank to another and by account type.
Are Wire Transfers Reversible?
Fedwire payments are final and irrevocable once processed. A bank can request a return, but getting the money back is not guaranteed after the transfer has been completed.
How Fast Is Same Day ACH?
Eligible Same Day ACH payments settle during the same banking day. Nacha reported 470.4 million of them in the third quarter of 2026, up 36.7% from a year earlier.
Which Is Better for Large Payments?
Wires are widely used for large, urgent payments because of real-time settlement and finality. ACH can still carry large payments, depending on network rules and each bank's own limits.
Resources
- Nacha: How ACH Payments Work
- Nacha: Q3 2026 ACH Network Statistics
- Nacha: ACH Payments Fact Sheet
- Nacha: Funds Availability Requirements for Non-Same Day Credits
- Federal Reserve: Fedwire Funds Service Overview
- Federal Reserve Financial Services: Fedwire Funds Service
- Federal Reserve Financial Services: Fedwire Monthly Statistics, September 2026
- Federal Reserve Financial Services: 2026 FedACH Fees
- CFPB: Electronic Fund Transfers FAQs
- CFPB: Regulation E Remittance Cancellation Rule